
AR Model: Formula, Illustrative Results, Charts and Interpretation
AR Model models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients. This independently written guide explains the method, native MathML formula, illustrative 649-record G3 computation (not longitudinal data), assumptions, Python, R, SPSS and Excel workflows, matching charts and downloads, diagnostics, reporting, and contextual internal links.
Important: student CSV row order is not a time index
The 649 observations used here are individual student records, not repeated measurements collected at regular dates. The dataset provides no observation-date field, so the original CSV row order does not establish a chronological sequence. Any models, lag tests, seasonal cycles, fitted trends, charts, and holdout estimates produced from that order must be treated as illustrations of numerical procedures only; they do not establish real temporal patterns, validated future forecasts, or causal relationships.
For actual time-series analysis, use longitudinal observations with a known date index and defensible sampling frequency, verify spacing and diagnostics, and evaluate on later observations. The numerical examples and linked downloads here have not been independently recomputed in this correction.
AR Model worked-example conclusion
Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143.
What is AR Model?
The exact statistical or forecasting target.
AR Model models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients. The correct interpretation begins with this target and not with a software label, attractive chart, or isolated p-value.
What the method answers
AR Model is used to turn a chronological research question into an explicit model, statistic, or evaluation rule. In this article the uploaded CSV contributes 649 ordered student records. Records 1–584 are used for fitting and records 585–649 form the 65-record holdout whenever forecasting is relevant.
Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143.
What the method does not answer
AR Model does not remove the need to inspect data quality, time spacing, deterministic structure, missing periods, structural changes, residual behavior, and forecast horizon. It also does not turn predictive association into experimental causation or a nonsignificant test into proof of exact equality.
Use the method together with ARIMA Model; ARMA Model; MA Model; SARIMA Model; Autocorrelation Function.
When should AR Model be used?
A research-question-first decision.
Define the target
State whether the goal is identification, estimation, diagnostics, stability, smoothing, causality, cointegration, or forecast evaluation.
Verify the index
Sort dates, resolve duplicates, and insert expected missing periods before constructing lags.
Declare frequency
The CSV has no date field. A 12-record period is used only where the supplied method assets require a repeatable computational cycle; it must not be described as calendar seasonality.
Choose specification
Fix deterministic terms, lag order, transformation, seasonal structure, and validation horizon.
Audit the output
Reconcile statistics, charts, residuals, software defaults, and matching downloads.
Uploaded student dataset for AR Model
A reproducible calculation from dataset(100).csv.
Data design
The source is dataset(100).csv, containing 649 student records and 33 columns. G3 final grade is the primary numeric sequence. G2 is the aligned secondary sequence for VAR, VECM, Granger-causality, and cointegration demonstrations. The original row order is preserved exactly; no synthetic dates, values, trends, or seasonal components are added.
Validation design
Records 1–584 form the training sequence. Records 585–649 form the untouched 65-record holdout. Parameter selection and transformations use training records only. The same uploaded row order is retained in Python, R, SPSS, and Excel so differences can be traced to software conventions rather than to different samples.
AR Model assumptions and data conditions
Non-negotiable checks before interpretation.
Condition 1
The time index is correctly ordered and duplicate timestamps are resolved.
Condition 2
The declared lag structure is feasible for the available sample size.
Condition 3
The residual mean is approximately zero after deterministic terms are included.
Condition 4
Residual dependence is checked rather than assumed away.
Condition 5
Parameter stability is evaluated across the modeled period.
Condition 6
Forecast validation preserves temporal order and does not randomly shuffle observations.
AR Model formula and notation
Rendered with browser-native MathML.
The symbols must be mapped to the actual series, time index, lag order, error, state, or system used in the analysis. Do not copy the notation without stating the frequency and parameter specification.
Formula interpretation
For AR Model, the equation operationalizes the purpose described above. Each lag, state, residual, difference, coefficient, or error term has a temporal meaning. The worked output is interpreted through the complete structure rather than through one coefficient in isolation.
Calculation control
Keep full precision in intermediate calculations, round only for display, and reconcile the software output with the formula. The matching Excel workbook is especially useful for checking range alignment, while Python and R support repeatable model estimation and diagnostics.
AR Model illustrative worked results
Exact values from the common example.
| Result field | Value | Audit note |
|---|---|---|
| AR(1) | 0.204 | Uploaded 649-record G3 example; retain full precision in calculations |
| AR(2) | 0.180 | Uploaded 649-record G3 example; retain full precision in calculations |
| Holdout RMSE | 5.143 | Uploaded 649-record G3 example; retain full precision in calculations |
| Final forecast | 10.946 | Uploaded 649-record G3 example; retain full precision in calculations |
AR Model in Python
Reproducible calculation and validation.
from statsmodels.tsa.ar_model import AutoReg

fit = AutoReg(train, lags=2, trend='ct', old_names=False).fit()

forecast = fit.predict(start=len(train), end=len(train)+11)
For real time-series inference, use genuinely time-indexed observations with verified spacing, perform a temporal holdout, and inspect residual diagnostics. The student-row example below lacks an observation-date index, so its results are computational demonstrations, not validated forecasts. The supplied Python charts and PDF belong only to this AR Model post.
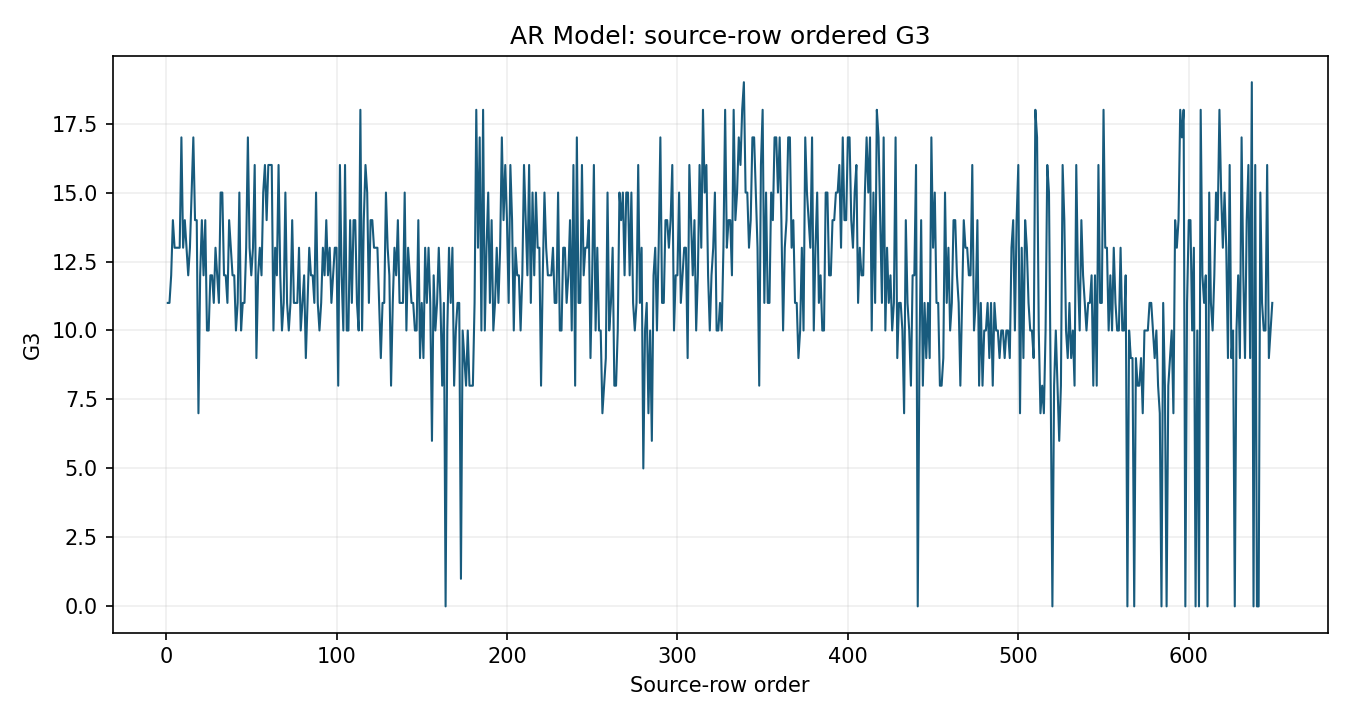
Python chart 1: AR Model
The Python figure for AR Model presents the source series and time ordering. Its file name is ar model 01 source series. Interpret this chart with the worked statistics and the matching Python PDF; the image alone does not establish the final inference.
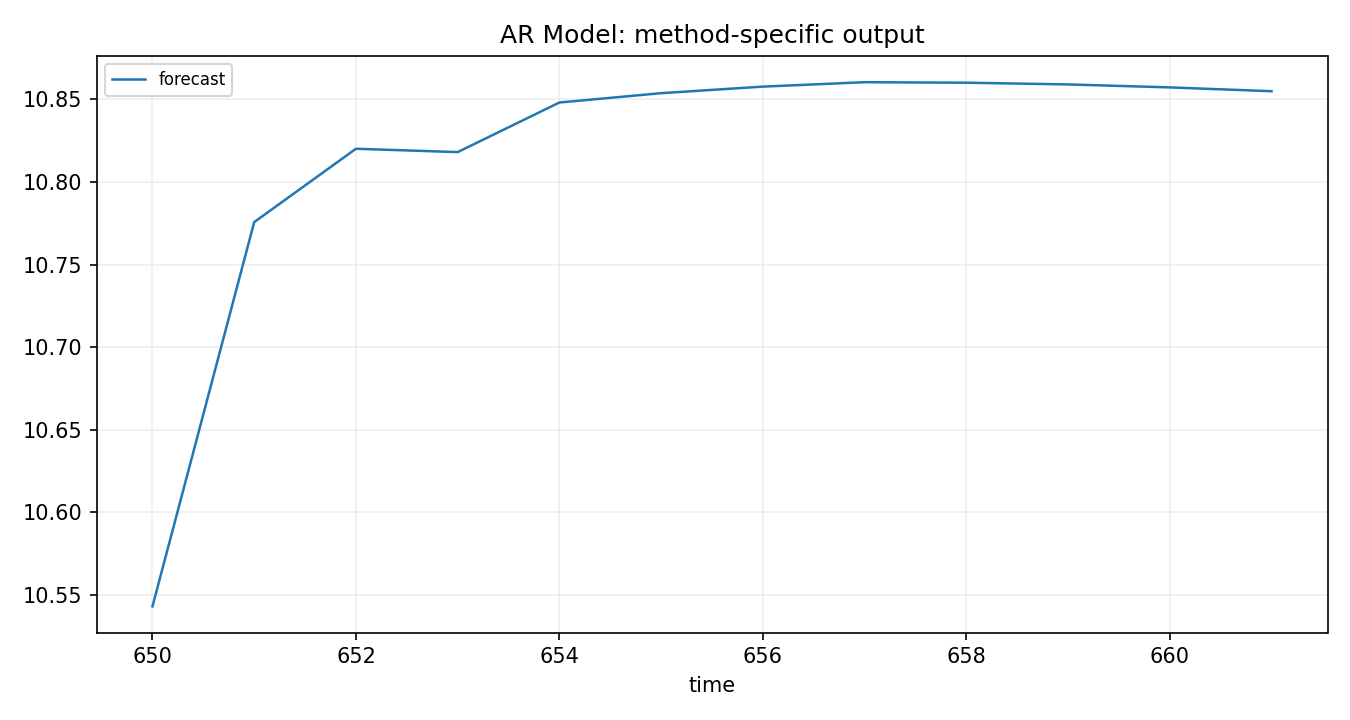
Python chart 2: AR Model
The Python figure for AR Model presents the method-specific fitted or transformed output. Its file name is ar model 02 method output. Interpret this chart with the worked statistics and the matching Python PDF; the image alone does not establish the final inference.
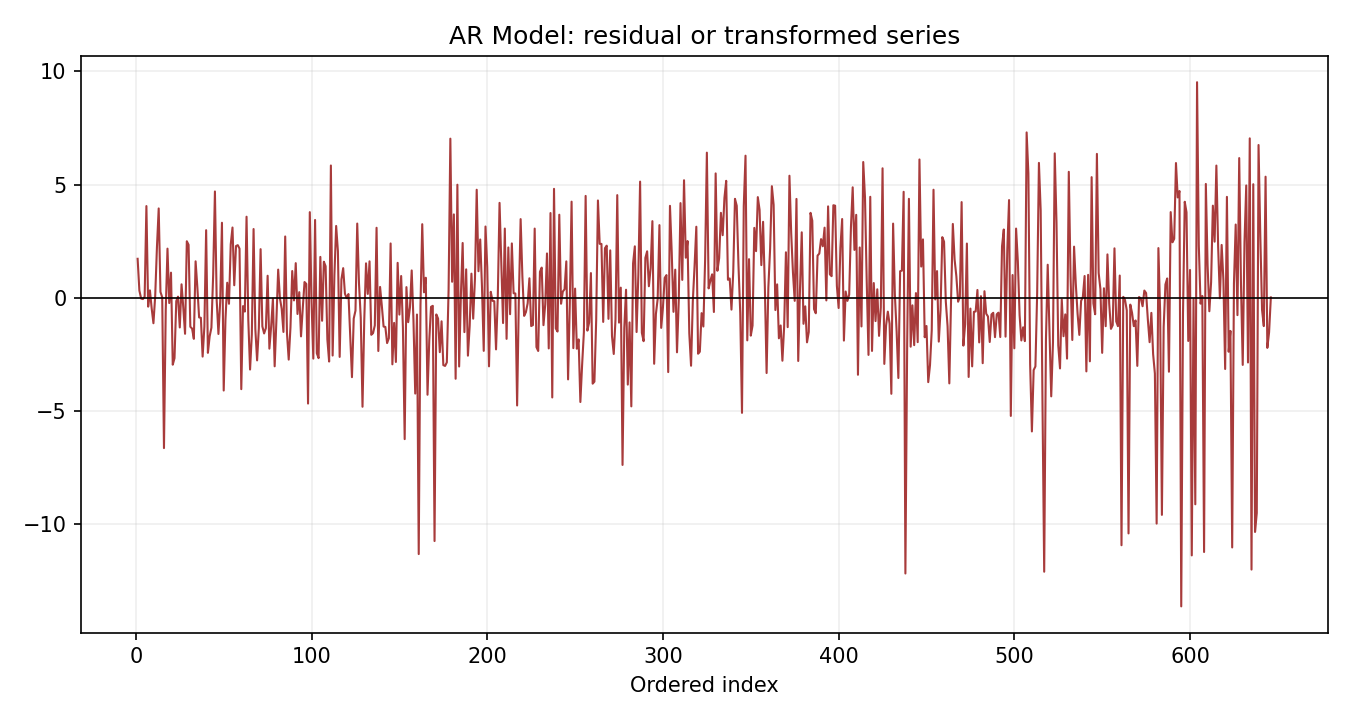
Python chart 3: AR Model
The Python figure for AR Model presents the residual path through time. Its file name is ar model 03 residual path. Interpret this chart with the worked statistics and the matching Python PDF; the image alone does not establish the final inference.
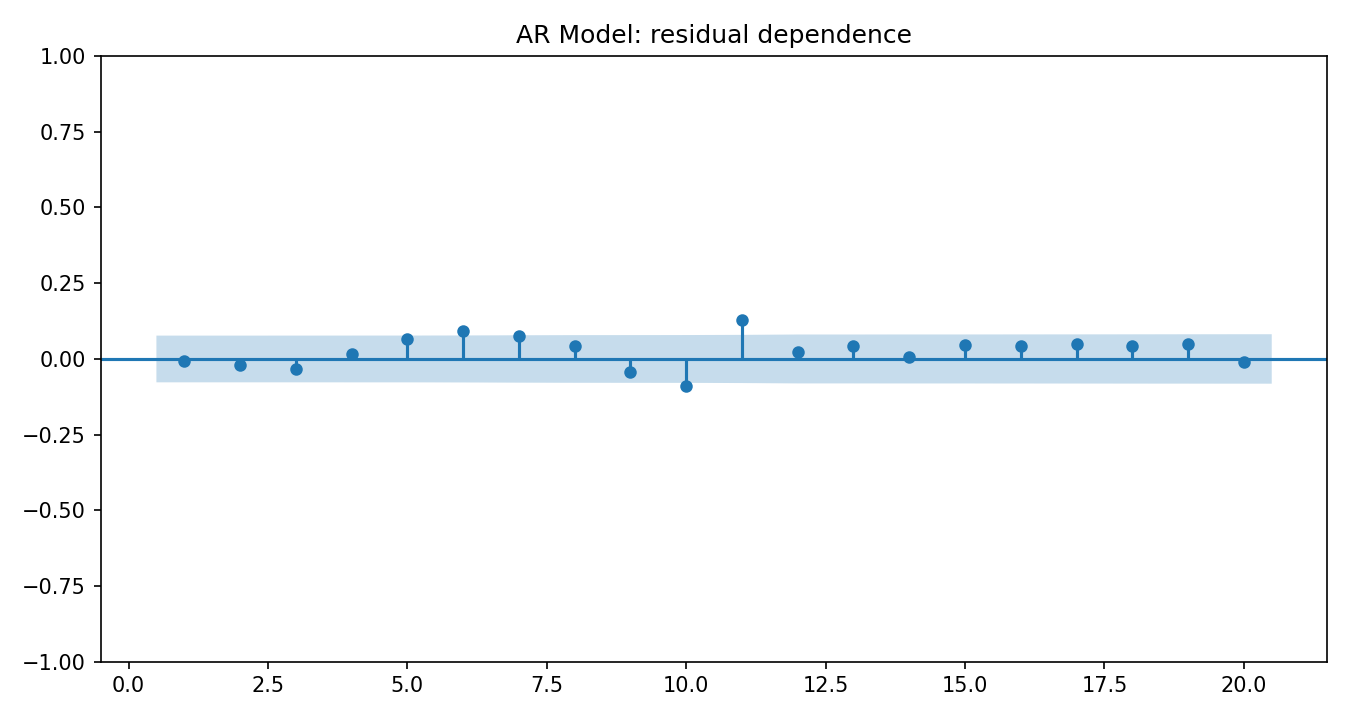
Python chart 4: AR Model
The Python figure for AR Model presents the residual autocorrelation diagnostics. Its file name is ar model 04 residual acf. Interpret this chart with the worked statistics and the matching Python PDF; the image alone does not establish the final inference.
Python chart 5: AR Model
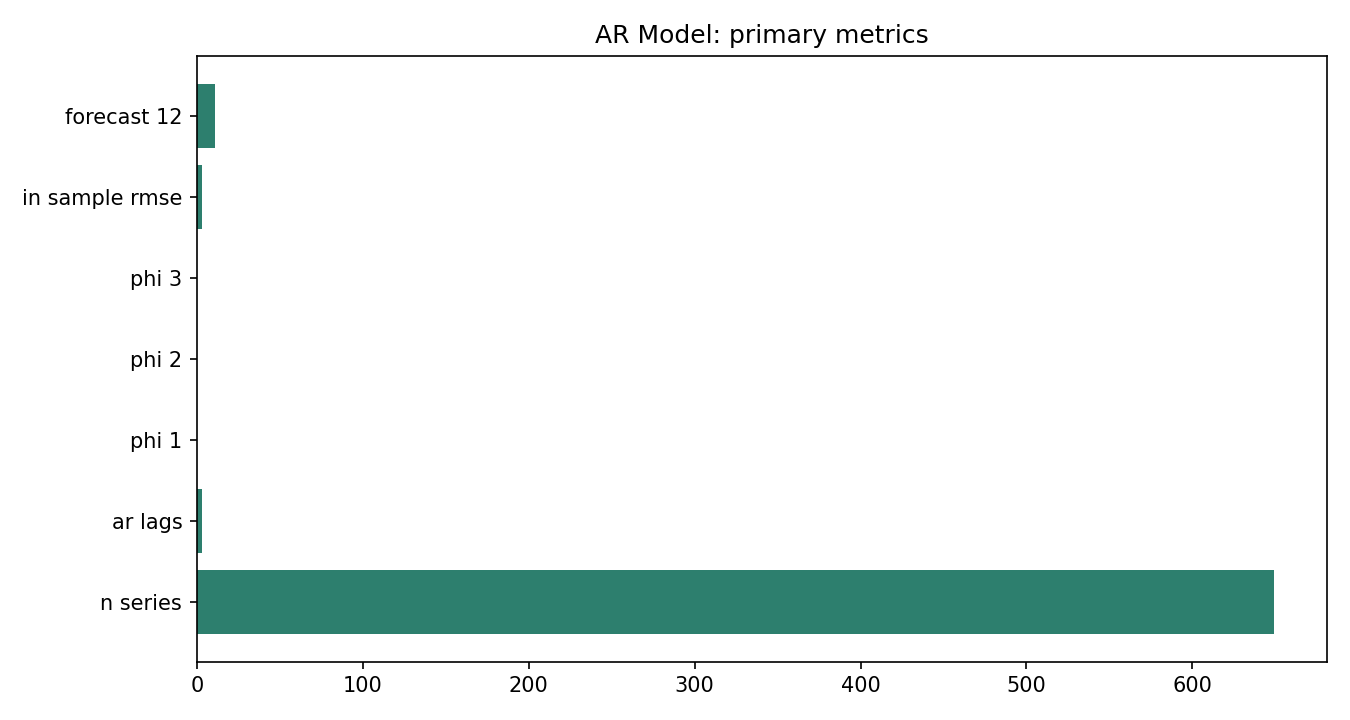
The Python figure for AR Model presents the primary statistics and validation metrics. Its file name is ar model 05 primary metrics. Interpret this chart with the worked statistics and the matching Python PDF; the image alone does not establish the final inference.
AR Model in R
Equivalent specification with explicit frequency.
fit <- arima(train, order=c(2,0,0), include.mean=TRUE)

predict(fit, n.ahead=12)
The R workflow must use the same start date, frequency, training endpoint, lag order, deterministic structure, and forecast horizon. Reconcile default initialization, missing-value behavior, coefficient signs, and critical values before comparing numerical output with Python.
R chart 1: AR Model
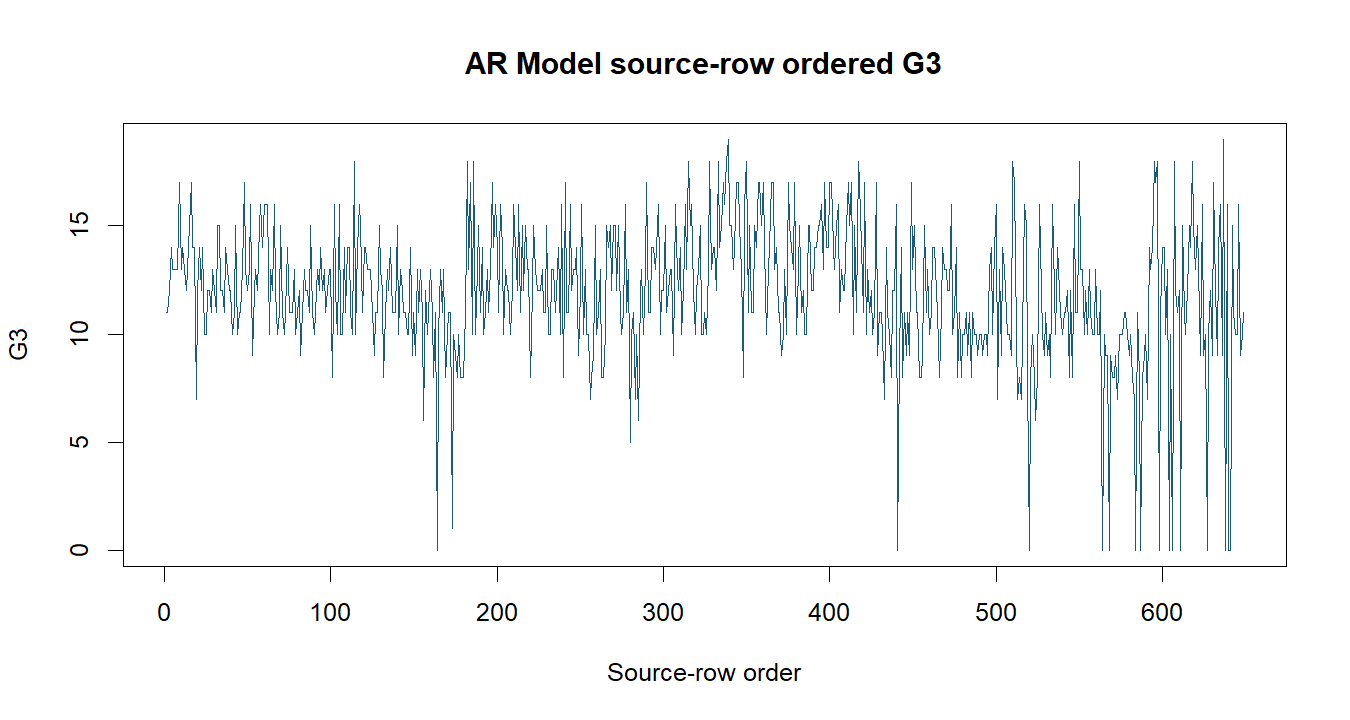
The R figure for AR Model presents the source series and time ordering. Its file name is ar model 01. Interpret this chart with the worked statistics and the matching R PDF; the image alone does not establish the final inference.
R chart 2: AR Model
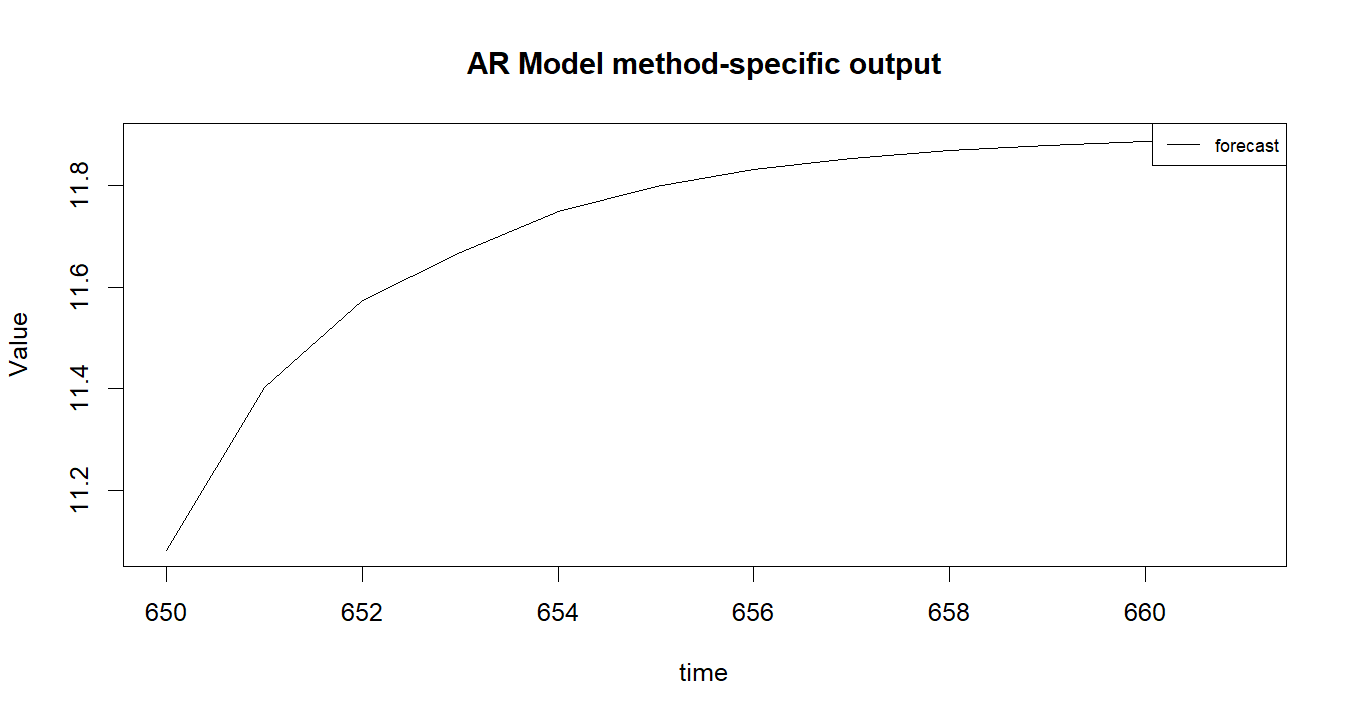
The R figure for AR Model presents the method-specific fitted or transformed output. Its file name is ar model 02. Interpret this chart with the worked statistics and the matching R PDF; the image alone does not establish the final inference.
R chart 3: AR Model
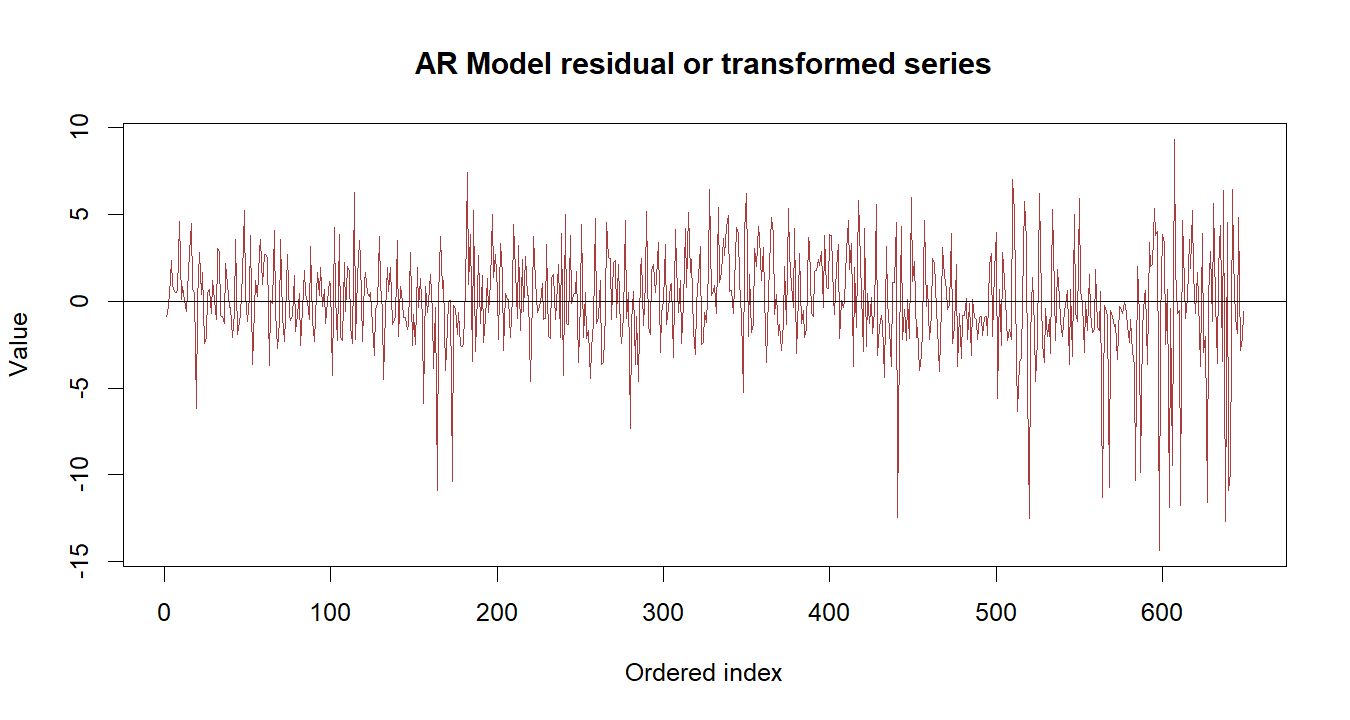
The R figure for AR Model presents the residual path through time. Its file name is ar model 03. Interpret this chart with the worked statistics and the matching R PDF; the image alone does not establish the final inference.
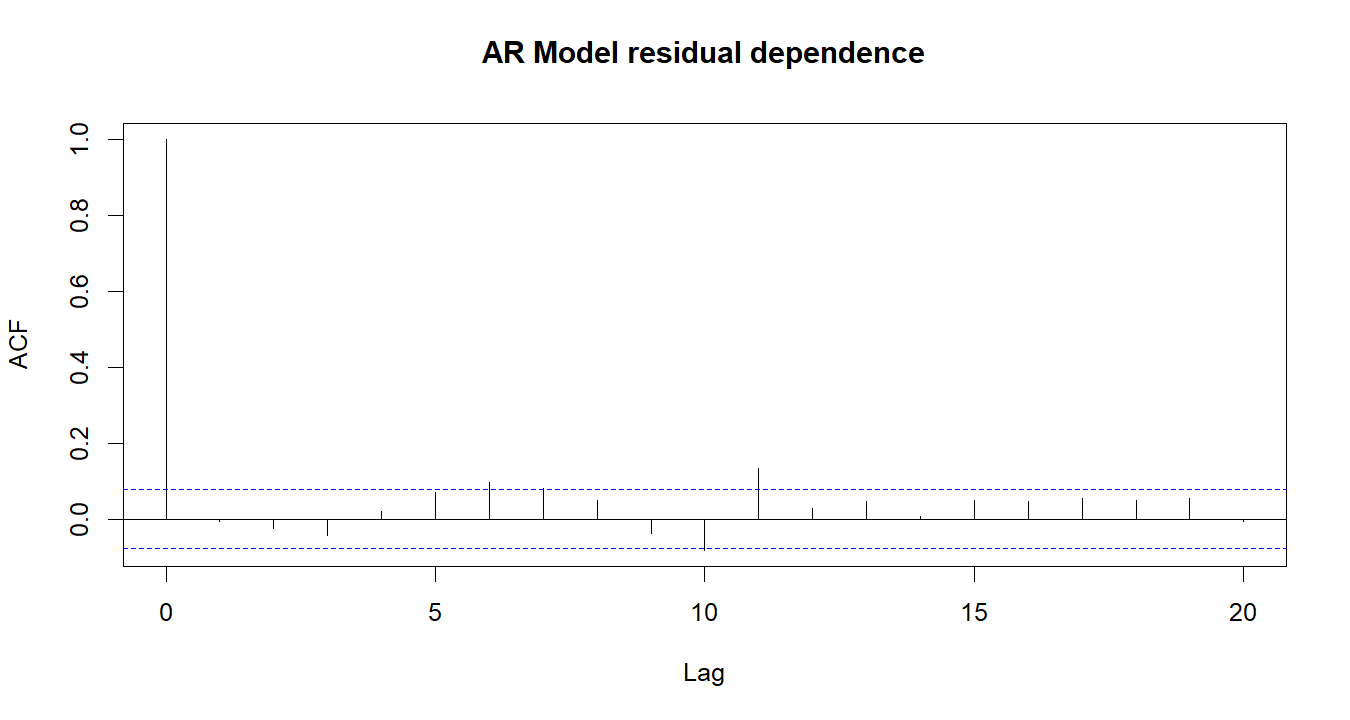
R chart 4: AR Model
The R figure for AR Model presents the residual autocorrelation diagnostics. Its file name is ar model 04. Interpret this chart with the worked statistics and the matching R PDF; the image alone does not establish the final inference.
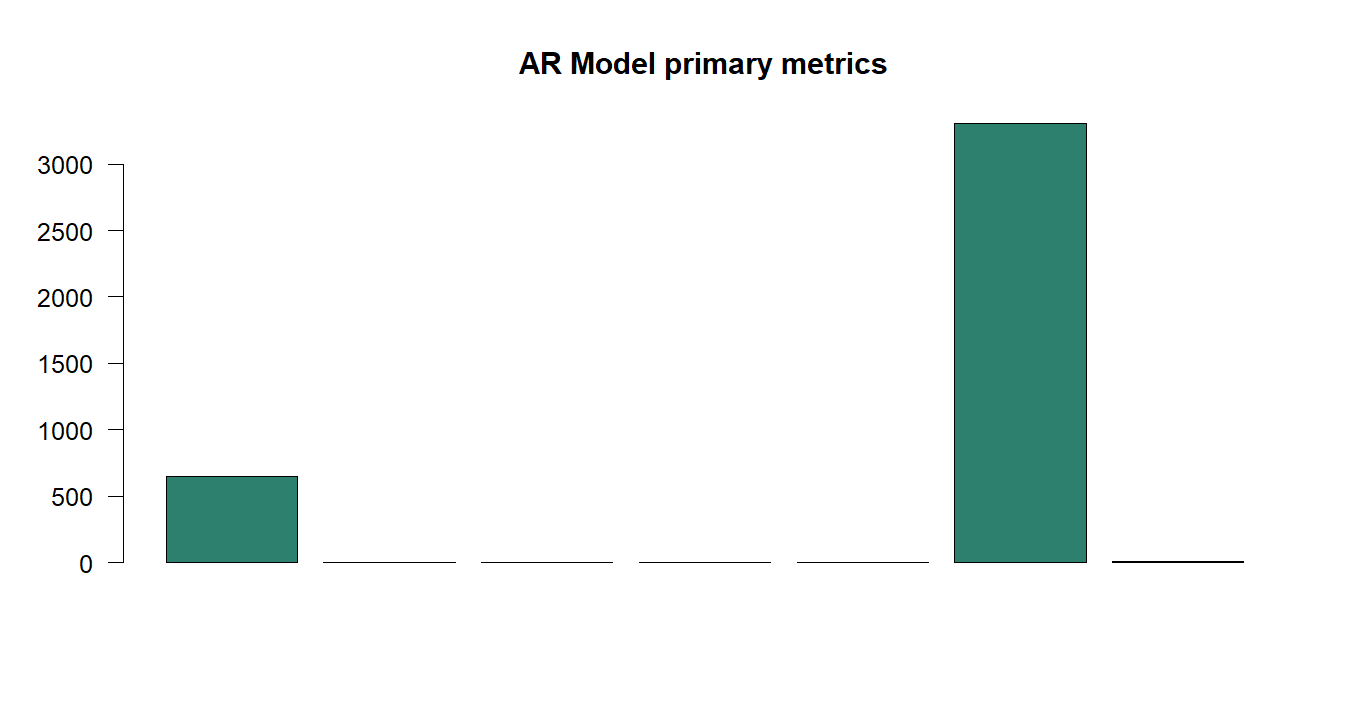
R chart 5: AR Model
The R figure for AR Model presents the primary statistics and validation metrics. Its file name is ar model 05. Interpret this chart with the worked statistics and the matching R PDF; the image alone does not establish the final inference.
AR Model in SPSS
Use only procedures SPSS genuinely supports.
Use Analyze > Forecasting > Create Models or validated syntax. Set the exact date frequency, declare transformations and lag orders, save residuals, and export the model summary plus residual ACF/PACF. SPSS may label ARIMA components differently, so reconcile signs and differencing conventions with the formula shown here.
AR Model in Excel
A transparent formula and range audit.
Arrange record number in column A, G3 in column B, and lagged values in adjacent columns. Estimate coefficients with LINEST or the Regression tool, calculate fitted values row by row, and reserve the final 65 rows for untouched holdout forecasts. Recursive forecasts must use prior forecasts where actual lagged observations are unavailable.
How to interpret AR Model charts
Each chart has a distinct technical role.
Source or input chart
Check order, missing periods, changing level, seasonality, outliers, and possible breaks before fitting. A visually attractive series is not automatically stationary or forecastable.
Method-output chart
Compare fitted and observed behavior or the method-specific transformation. Look for systematic misses, phase errors, and delayed responses rather than only visual closeness.
Residual and metric charts
Residual paths and autocorrelation show what predictable structure remains. Metric panels summarize holdout performance but must retain the horizon and units.
AR Model diagnostics and failure checks
Evidence that the result is usable.
Deep technical review of AR Model
Forty-eight topic-specific audit perspectives.
Temporal order. For AR Model, this review point concerns why the sequence must remain chronological and how random shuffling would leak future information. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Frequency declaration. For AR Model, this review point concerns how monthly, quarterly, daily, or irregular spacing changes lag meaning and seasonal interpretation. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Missing periods. For AR Model, this review point concerns how absent timestamps differ from observed zero values and how each should be represented. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Duplicate timestamps. For AR Model, this review point concerns how multiple records at one time point require an explicit aggregation or disaggregation rule. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Units and scaling. For AR Model, this review point concerns how coefficients and error summaries inherit the outcome scale and how transformations alter interpretation. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Log transformation. For AR Model, this review point concerns when multiplicative growth or variance stabilization supports a log scale and when zeros make it unsuitable. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Differencing. For AR Model, this review point concerns how regular and seasonal differences remove stochastic trends but also change the target being modeled. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Deterministic trend. For AR Model, this review point concerns why an intercept, time trend, or seasonal dummies must reflect the scientific specification. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Seasonal period. For AR Model, this review point concerns how a period of 12 for monthly data differs from a vague visual cycle and must be declared before estimation. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Lag order. For AR Model, this review point concerns how information criteria, domain timing, residual diagnostics, and sample size jointly constrain lag selection. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Parameter signs. For AR Model, this review point concerns how positive and negative coefficients affect persistence, correction, oscillation, or response direction. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Parameter magnitude. For AR Model, this review point concerns why a numerically large coefficient is not automatically important without considering the full dynamic polynomial. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Model admissibility. For AR Model, this review point concerns how stationarity, invertibility, positivity, or rank restrictions protect the mathematical process. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Initial conditions. For AR Model, this review point concerns how early state values or unavailable lags influence fitting and why software defaults should be recorded. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Optimization convergence. For AR Model, this review point concerns how a returned result can still be unreliable when the likelihood optimizer stops at a boundary or local solution. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Residual mean. For AR Model, this review point concerns why systematic residual bias indicates an omitted level, trend, transformation, or deterministic component. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Residual autocorrelation. For AR Model, this review point concerns why remaining serial structure means the model has not extracted all predictable timing information. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Residual variance. For AR Model, this review point concerns how changing error spread affects standard errors, intervals, and the relative value of volatility models. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Residual distribution. For AR Model, this review point concerns why heavy tails and outliers can make normal-based intervals too narrow even when point forecasts look reasonable. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Outlier timing. For AR Model, this review point concerns how isolated shocks, additive outliers, and level shifts require different interpretations and interventions. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Structural breaks. For AR Model, this review point concerns how policy, measurement, market, or operational changes can invalidate a single stable-parameter model. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Training endpoint. For AR Model, this review point concerns why every tuning choice must use observations available at or before the declared forecast origin. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Holdout horizon. For AR Model, this review point concerns how one-step and twelve-step performance answer different operational forecasting questions. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Rolling-origin validation. For AR Model, this review point concerns how repeated forecast origins reveal whether one favorable split is representative. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Baseline comparison. For AR Model, this review point concerns why a naive, seasonal-naive, or simple smoothing forecast is needed before claiming improvement. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Metric selection. For AR Model, this review point concerns how MAE, RMSE, MAPE, information criteria, and statistical tests answer different questions. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Forecast intervals. For AR Model, this review point concerns why uncertainty should widen with horizon and why point accuracy alone is incomplete. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Small samples. For AR Model, this review point concerns how parameter count, lag loss, and unstable asymptotics become especially important with short histories. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Large samples. For AR Model, this review point concerns why tiny p-values can coexist with operationally negligible effects and why diagnostics still matter. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Multiple series. For AR Model, this review point concerns how comparing or combining series requires aligned calendars and consistent transformations. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Exogenous variables. For AR Model, this review point concerns how external predictors must be known or forecast at future horizons to support genuine forecasts. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Data leakage. For AR Model, this review point concerns how centered moving averages, full-sample scaling, or future-informed imputation can contaminate validation. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Software defaults. For AR Model, this review point concerns why default trends, lag selection, missing-value handling, and parameter signs can differ across programs. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Numerical precision. For AR Model, this review point concerns why displayed rounding should not replace full-precision calculations or reconciliation tables. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Chart interpretation. For AR Model, this review point concerns how the source-series, fitted-output, residual-path, residual-ACF, and metric charts answer different questions. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Chart accessibility. For AR Model, this review point concerns why meaningful alt text should state the variable, method, comparison, and visible conclusion. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Download integrity. For AR Model, this review point concerns why each PDF and workbook must belong only to the matching topic and preserve the same sample and specification. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Reproducibility. For AR Model, this review point concerns how a complete audit trail records data version, code version, random seed, specification, and exported results. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Decision language. For AR Model, this review point concerns why fail-to-reject wording is different from proving a null model or exact equality. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Practical significance. For AR Model, this review point concerns how statistical evidence must be connected to the size and consequence of the dynamic effect. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Sensitivity analysis. For AR Model, this review point concerns how alternate lag orders, transformations, break dates, and seasonal periods test robustness. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Model parsimony. For AR Model, this review point concerns why unnecessary parameters increase variance, complicate interpretation, and can worsen future performance. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Model underfit. For AR Model, this review point concerns why a simple model can leave visible structure even when its in-sample error appears acceptable. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Model overfit. For AR Model, this review point concerns why an elaborate model can absorb historical noise and fail at later forecast origins. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Documentation. For AR Model, this review point concerns why the final report should state frequency, sample, transformations, lag orders, diagnostics, holdout design, and software. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Operational use. For AR Model, this review point concerns how update frequency, retraining rules, monitoring thresholds, and fallback forecasts turn analysis into a maintainable process. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Ethical interpretation. For AR Model, this review point concerns why forecasts and time-series tests should not be presented as certainty when decisions affect people or resources. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
Internal navigation. For AR Model, this review point concerns how links to related methods help readers move from identification to estimation, diagnostics, and forecast evaluation. The method specifically models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients; therefore the analyst should connect this issue to the lag polynomial, differencing choices, innovation process, and recursive forecast path. In the worked example, Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. That numerical result is useful only when the date index, training endpoint, and declared frequency remain unchanged. A defensible audit records the choice before seeing the final forecast error or p-value, checks the matching chart and software output, and explains whether the conclusion would change under a reasonable alternative. Related guidance appears in ARIMA Model, ARMA Model, MA Model, but those methods answer different parts of the identification, estimation, diagnostic, or validation problem.
What should AR Model be compared with?
Method choice and robustness checks.
| # | Comparison | Reason |
|---|---|---|
| 1 | Compare simpler lag orders with information criteria and holdout errors. | AR Model remains the focal method; the comparison prevents a mismatch between the research question and the software command. |
| 2 | Compare differencing-based models with trend or seasonal-state alternatives. | AR Model remains the focal method; the comparison prevents a mismatch between the research question and the software command. |
| 3 | Compare residual ACF, Ljung–Box results, and forecast calibration before choosing a final model. | AR Model remains the focal method; the comparison prevents a mismatch between the research question and the software command. |
How to report AR Model
A complete, restrained result statement.
Reporting template
“A AR Model analysis was completed on 649 records from dataset(100).csv. G3 was the primary ordered sequence, G2 was used where a second aligned variable was required, records 1–584 were used for estimation, and records 585–649 were used for validation where applicable. Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. The date frequency, transformation, deterministic terms, lag or seasonal specification, residual diagnostics, software, and matching files were recorded. The conclusion is limited to this specification and does not establish certainty beyond the analyzed period.”
Include
Dataset filename, row count, sequence definition, variable roles, transformation, lag order, computational cycle where used, formula, exact result, p-value or accuracy metric, diagnostics, validation horizon, software, and limitations.
Avoid
Claims of proof from nonsignificance, causal language from predictive precedence, arbitrary random train/test splits, unlabeled software defaults, hidden missing-value deletion, or charts without matching numerical evidence.
AR Model downloads
Only files assigned to this topic in the supplied workbook.
AR Model frequently asked questions
Method-specific answers for publication review.
What does AR Model measure?
AR Model models the current observation as a regression on its own earlier values, making serial dependence explicit through autoregressive coefficients. It should be interpreted through its exact formula, data frequency, lag or horizon choices, and the diagnostic evidence shown in this article.
When should AR Model be used?
Use AR Model when the research question directly matches that purpose and the chronological design can satisfy the listed assumptions. Do not choose it merely because the software menu contains a similarly named option.
What assumptions matter most for AR Model?
The most important conditions are correct time ordering, explicit frequency, defensible lag or seasonal structure, suitable deterministic terms, and a validation plan that never uses future observations during fitting.
How is the AR Model result interpreted?
Using G3 in the uploaded dataset, the AR(2) fit estimated lag coefficients 0.204 and 0.180; the final 65-record holdout RMSE was 5.143. The result is conditional on the displayed specification and does not prove that every alternative model or data transformation would lead to the same conclusion.
Can AR Model be completed in Python?
Yes. The Python section gives a reproducible core calculation. Preserve the date index, software version, parameter choices, and holdout dates when comparing the output with the supplied PDF.
Can AR Model be completed in R?
Yes. The R section states the corresponding workflow. Differences in default initialization, signs, critical values, or missing-value handling must be reconciled before declaring the programs inconsistent.
How should SPSS be used for AR Model?
SPSS should be used only for procedures it genuinely supports. The workflow explains when standard dialogs are sufficient and when validated Python/R integration or a transparent auxiliary regression is required.
How can Excel support AR Model?
Excel is valuable for a visible audit trail. Named parameter cells, explicit lag ranges, separate training and holdout rows, and formula checks reduce hidden range errors.
What is the most common AR Model mistake?
The most common mistake is interpreting a statistic or forecast without verifying the underlying sequence, specification, residual diagnostics, and validation horizon.
How should charts be interpreted for AR Model?
Read the first chart as the data or method context, later charts as fitted behavior and residual evidence, and the metrics chart as a summary. No single image replaces the formal calculation.
How should AR Model be reported?
Report the dataset filename, row count, sequence definition, transformations, model or test specification, result values, diagnostics, software, holdout design, and a conclusion that matches the null hypothesis or forecast target.
Which internal guides are related to AR Model?
The most relevant internal guides are ARIMA Model, ARMA Model, MA Model, SARIMA Model, Autocorrelation Function. Each is linked in the related-guides panel and used only because it supports the same time-series workflow.